Bridge the gap between lecture-hall theory and live markets. Bryzenta uses adaptive predictive models to align high-frequency data with your personal risk profile, automating your entry into digital assets without manual guesswork.
Bryzenta was designed around a simple observation: students studying finance, economics and computer science already understand risk mathematics, but rarely have a disciplined way to apply it with limited capital.
The platform combines reinforcement learning with a transparent risk-scoring layer, so every automated adjustment can be traced back to a measurable variable rather than a hidden signal. You define the constraints; the model operates within them.
Bryzenta never custodies your funds. Connections run through encrypted, permission-restricted API keys, so withdrawal rights stay with you at all times.
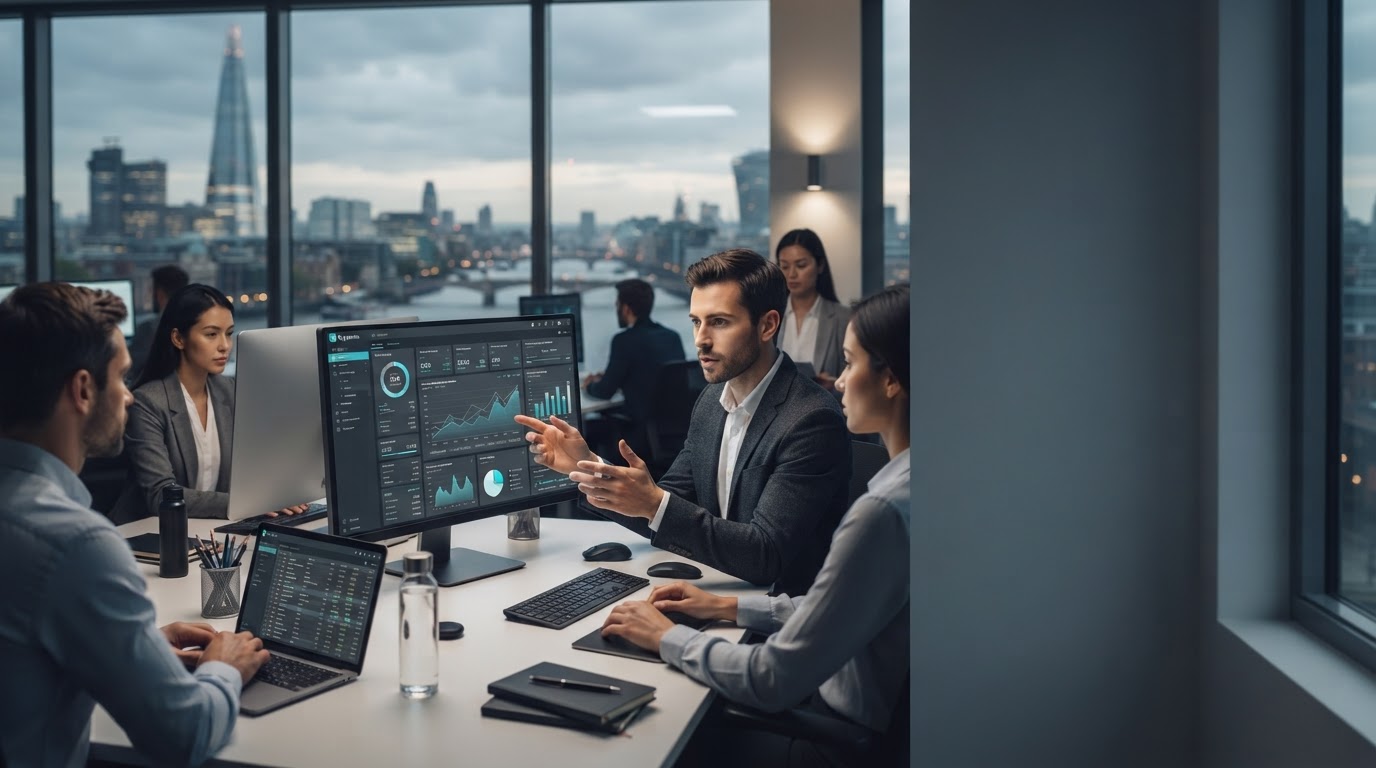
Unlike static bots that follow fixed rules, Bryzenta's engine monitors your downside variance continuously. It does not simply execute trades; it learns how much volatility your specific portfolio can absorb before it rebalances exposure.
Parameters you set during onboarding — capital limits, study schedule, acceptable drawdown — become the boundaries the model optimises within. Nothing is adjusted outside that range without your sign-off.
Each stage is designed to be reversible before the one after it. Capital only enters the market once a strategy has been tested against your own constraints.
Input your capital constraints and academic schedule to set monitoring windows and maximum position size.
The engine backtests your configuration against five years of historical tick data to validate the risk tolerance you have set.
Deploy with small-scale capital while the model refines entry points using predictive sentiment and order-book signals.
The dashboard favours density over decoration. Each module updates independently, so you can check a single metric without loading the full interface.
Aggregates social and news sentiment across major exchanges throughout each trading session.
Forecasts short-term volatility bands using historical tick data and current order-book depth.
Tracks how digital assets move relative to equities, bonds and currency pairs you may already study in class.
Surfaces downside variance, drawdown and current exposure in a single, continuously updated readout.
These are illustrative behaviours, not guaranteed outcomes. Markets remain unpredictable; the model is built to reduce unnecessary exposure, not to eliminate risk.
| Scenario | Model Response |
|---|---|
| High-exam period | Monitoring windows narrow and the model increases stop-loss sensitivity, reducing position sizing automatically for the duration you specify. |
| Flash crash | Predictive models flag liquidity gaps in the order book and pause execution rather than fill orders into poor pricing. |
| Sideways market | Exposure shifts toward delta-neutral strategies designed to preserve capital while directional signals remain weak. |
Most of our users ask about the underlying math before they ask about pricing. These are the questions that come up first.
We use Value at Risk (VaR) and Conditional Value at Risk (CVaR) metrics, recalculated roughly every 60 seconds from live exchange order books. Both figures are visible in the Portfolio Health Telemetry module, not hidden behind a single composite score.
Bryzenta never holds your funds directly. The platform connects to your exchange account through encrypted API keys with withdrawal permissions disabled by default.
No. The parameter-definition step is built to translate academic risk concepts — variance, correlation, drawdown — into account settings, so coursework knowledge transfers directly.
Yes. Every automated adjustment stays within the boundaries you set at onboarding, and you can pause live optimisation at any time from the dashboard.
Create an account to set your risk parameters and run a backtest against historical data before committing any capital. No obligation, no live trading until you choose to deploy it.